
Discover essential FX hedging strategies and currency management best practices from our foreign exchange experts.
Treasury Centralisation: Benefits for Global Finance Teams


In FX risk management, treasury centralisation means two things:
- External FX trades are executed only by Headquarters (HQ);
- FX policy is set by HQ for the entire group.
Companies with international operations centralise treasury FX risk management to reduce costs and improve cash visibility. This blog explains how Currency Management Automation can help your firm reap the benefits of FX centralisation by:
- reducing the cost of currency management
- optimising exposure netting at group level
- enhancing control over FX policy
- achieving better visibility
- optimising forward points management.
What is Treasury Centralisation?
Treasury professionals have long recognised the benefits of a centralised approach in terms of cash flow visibility, exposure netting and FX trading costs. Two conditions are necessary for centralised FX risk management to be effective:
- Headquarters (HQ) is solely responsible for the execution of external FX trades
- HQ sets a consolidated FX policy for the entire group.
The importance of FX centralisation is better understood by looking at a decentralised treasury setup, in which there is no uniform FX policy across the group and/or subsidiaries execute external FX transactions on their own. In such setups, the following problems tend to emerge:
- High FX trading costs. No group entity, whether HQ or a subsidiary, has enough ‘firepower’ to negotiate better terms with banks on its own.
- Reduced cash visibility. Limited visibility across group entities and dispersal of funds can make it difficult to access internal cash reserves.
- Siloed management. Different entities may pursue different FX management goals, making it difficult to integrate risk management.
- Weaker control. Decentralised models lack consolidated oversight and standardised processes, making it difficult to track risks on a global basis.
The 5 Benefits of Treasury Centralisation
The table below shows the key benefits of centralising FX management. Take exposure netting and forward points optimisation as examples. While these tasks can carry out these tasks on their own, centralisation dramatically expands their scope by taking a cross-subsidiaries approach.
A more direct way to reduce hedging costs is to concentrate all FX trades at HQ level. Witg greater ‘firepower’ (i.e., a higher volume of transactions), HQ can negotiate lower bid-ask spreads and strengthen the group’s relationships with banks.
Making HQ the sole entity allowed to execute external trades is a powerful control mechanism. Time and again, subsidiary managers are tempted by speculative, unauthorised FX trading, which often results in material losses. Finally, FX centralisation allows HQ treasury teams to see the P/L of trades, and their forward point impact, in real time.
How Automation Delivers Centralised Treasury
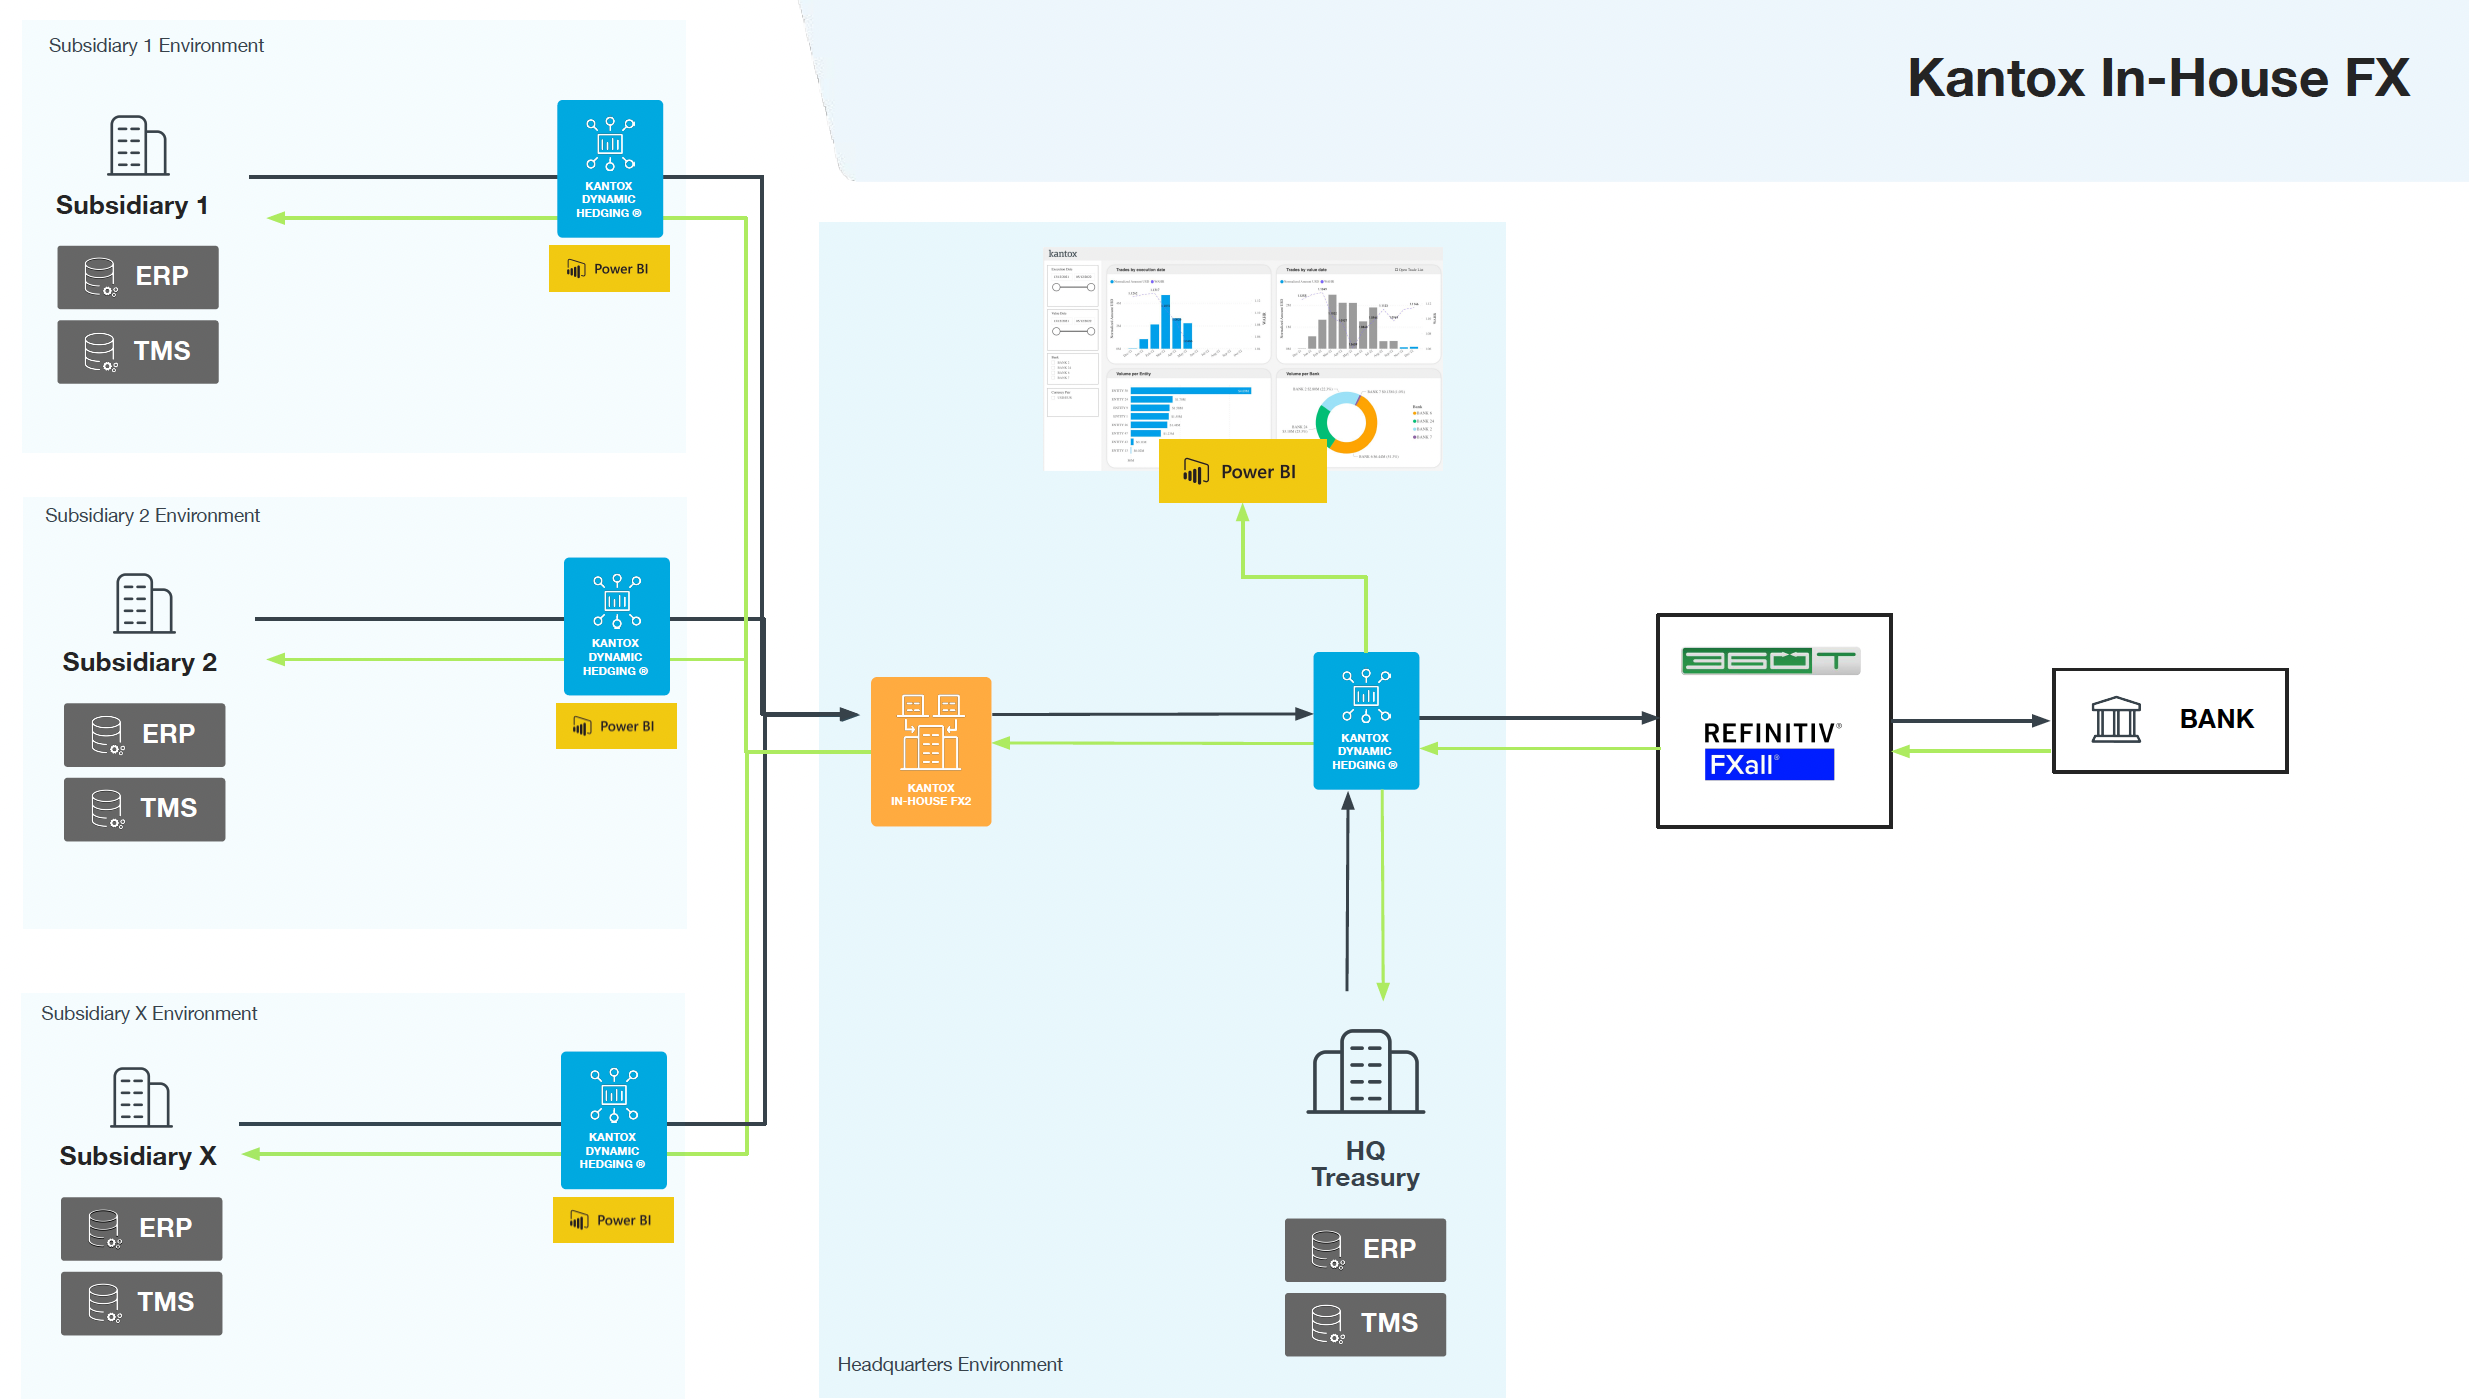
Kantox In-House FX is an automated solution designed for companies that want to centralise all their FX volume under a single trading entity. Subsidiaries carry out internal FX transactions, while HQ executes all external FX transactions with banks.
HQ acts as the group’s liquidity provider, giving subsidiaries 24/7 access to FX liquidity, with customisable markups and validation rules based on tenor, amount, timing and currency pair.
At subsidiary level, the benefits of Kantox In-House FX include:
- Segregation of FX policy, trading and accounting by subsidiary
- 24/7 internal FX liquidity with customisable markups set by HQ
- Netting and forward points optimisation at subsidiary level
At group level, the main benefits are:
- Better terms with banks, since only one entity executes external trades
- Netting and forward points optimisation at consolidated level
- Full end-to-end traceability and control with API connectivity
Should you centralise your treasury?
If you need better liquidity management, particularly in terms of visibility and control, a Currency Management Automation solution such as Kantox In-House FX can help immediately.
Centralising FX risk management also saves resources and reduces operational risk, through rules set by each treasury team. Real-time visibility across FX management is enhanced as well.
Finally, Headquarters (HQ) is not a “broker” between subsidiaries and banks. Instead, it has complete control over FX policy and external hedges, including markups.
FAQs


